# Choosing the Optimal Tax System for Doing Business in Ukraine

> When clients ask which tax system to choose for a business in Ukraine, we give them key criteria to find the best option. Here they are, with a real example.

[Home](https://www.uhy-prostir.com/en/index.html.md) › [Insights](https://www.uhy-prostir.com/en/blog-en/index.html.md) › [Expert explainers](https://www.uhy-prostir.com/en/blog-en/articles/index.html.md) · 2024-05-07 · Updated 2026-11-06 · 8 min

When clients ask us which tax system to choose for doing business in Ukraine, we usually give them a list of key criteria. These criteria help them decide on the best option themselves. In this article, we share these criteria. We will also:

- explain which tax systems exist for businesses in Ukraine and describe each of them;
- use an example to show what to look at when you choose a tax system, given the specific features of the business.

## Tax systems for businesses in Ukraine

The Tax Code of Ukraine sets out two main tax systems: the general system and the simplified system.

Key features of the general system.

- **Type of business entity.** It can be used by legal entities, sole proprietors registered in Ukraine (FOPs) and separate divisions.
- **Employees**. There is no limit on the number of employees.
- **Types of activity.** There is no limit on the list of permitted KVED codes (Ukraine’s classification of economic activities).
- **Income limit.** The law does not set any limits.
- **Taxation**. The mandatory taxes under the general system are:

*Corporate income tax at 18%*, calculated by the formula: profit = income minus expenses;

*value added tax (VAT) at 20% *is mandatory if taxable supplies over the last 12 calendar months exceeded UAH 1 million (excluding VAT).

*Taxes for employees: 22% unified social contribution (USC, Ukraine’s mandatory social security contribution) on their income (paid by the employer), 18% personal income tax (PIT) and 5% military levy (withheld from the employee).*

Depending on their activities, some business entities also pay land tax, property tax, excise tax and others.

- **Reporting and accounting**. Accounting and HR records are mandatory. So all companies under the general system must file a Corporate Income Tax Return and Financial Statements. Sole proprietors file a Declaration of Property Status and Income. If there are payments to individuals, they must be shown in a special Combined Report, and VAT payers also file a VAT Return.

Key features of the simplified system.

- **Type of business entity.** The simplified system is available to legal entities and FOPs. It has four taxpayer groups:

*Group I* suits FOPs who plan to provide household services to the public or sell at markets.

*Group II* may sell goods and provide services, but only to simplified-system taxpayers or to the public.

*Group III* is also open to legal entities and allows them to provide services to taxpayers under the general tax system.

Group IV is only for producers of agricultural products.

- **Employees**. Some groups have restrictions. For example, single tax Group I may not hire employees, and Group II may hire no more than 10 people.
- **Types of activity.** Some types of activity are prohibited, for example, mining and selling precious metals and stones (making and selling jewelry is allowed), bookmaking, currency exchange, financial intermediation, trading in motor vehicles and many others. You can find the full list in paragraph 291.5 of the Tax Code of Ukraine.
- **Income limit.** Each group has its own limit. Turnover must not exceed 167 minimum wages for Group I, 834 minimum wages for Group II and 1,167 minimum wages for Group III. In 2024, the Group III limit is UAH 8,285,700.
- **Taxation**. Entrepreneurs in Groups I and II pay the single tax at a fixed rate on income (turnover) for the reporting period. Group III pays 5% of turnover, or 3% for VAT payers. In addition, entrepreneurs pay USC for themselves at 22% of the minimum wage. If they have employees, the taxes are the same as under the general system.
- **Reporting and accounting**. There are no exceptions to the obligation to keep records, but they may be kept in a simplified way. The main report for everyone is the Single Tax Return, and companies also file annual financial statements. Simplified-system taxpayers also file the Combined Report and the VAT Return when needed.

Ukraine also has NGOs (non-governmental organizations), which act according to their statutory goals and do not aim to make a profit. Can NGOs use the general or simplified tax system? In 99% of cases, they cannot. However, there are situations when NGOs are VAT payers. And they may use the simplified tax system only if they are removed from the [Register of Non-Profit Institutions and Organizations](https://cabinet.tax.gov.ua/registers/non-profit).

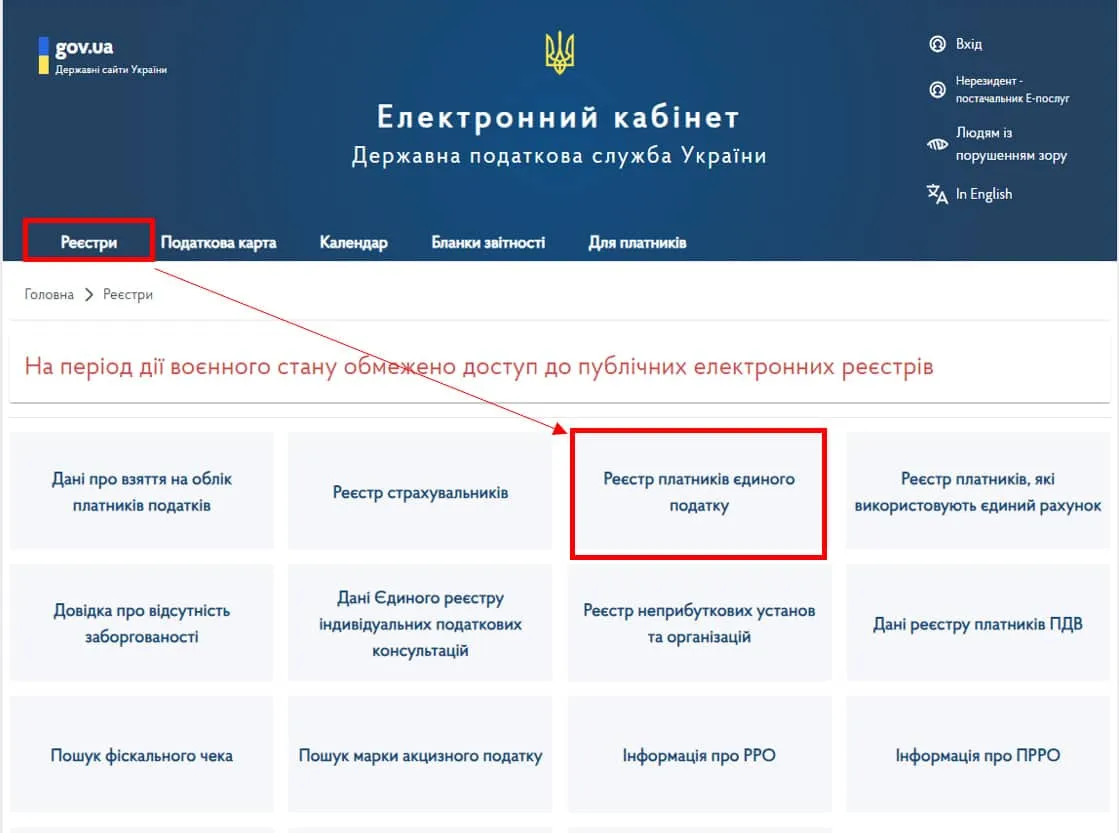
Entrepreneurs can always check which tax system they are on. They just need to use the [STS Electronic Cabinet](https://cabinet.tax.gov.ua/) (the online portal of the State Tax Service of Ukraine for taxpayers). Go to the Registers section and open the [Register of Single Tax Payers](https://cabinet.tax.gov.ua/registers/edpod)

<img src="/uploads/photo_2024-05-10_08-16-41.webp" alt="" width="1119" height="833" loading="lazy" decoding="async"/>

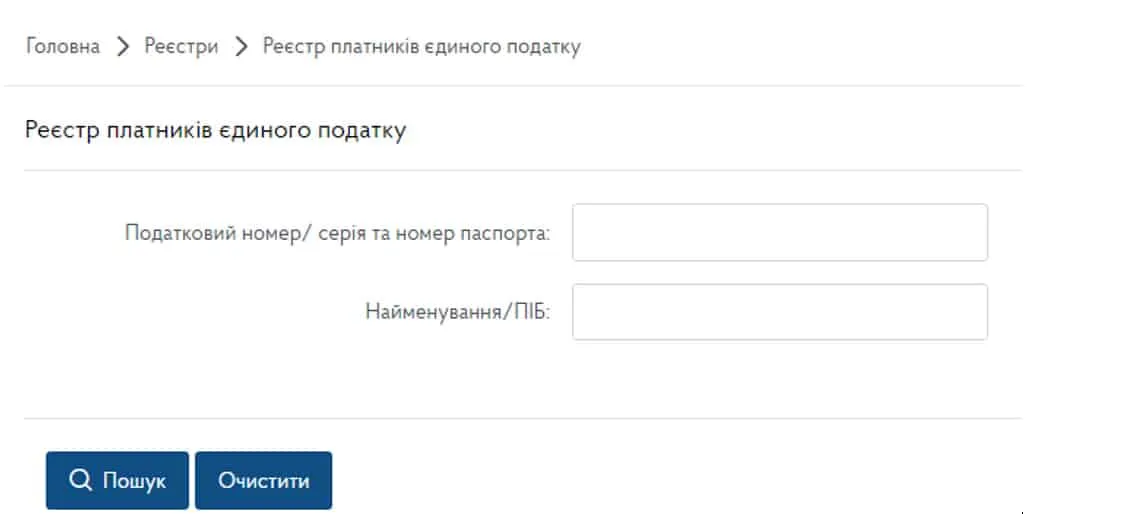
and enter the taxpayer’s number or name.
<img src="/uploads/photo_2024-05-10_08-18-56.webp" alt="" width="1121" height="514" loading="lazy" decoding="async"/>

If this register has no data on you, you are on the general system.

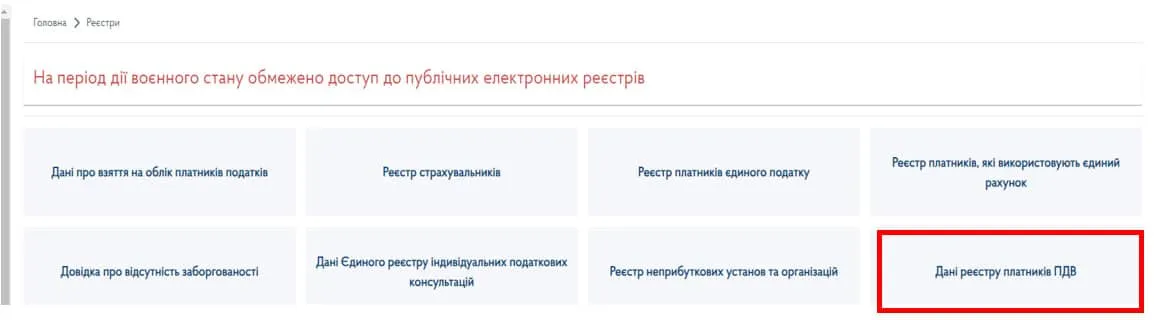
You can see your VAT payer status in the [VAT Payer Register Data](https://cabinet.tax.gov.ua/registers/pdv) section.
<img src="/uploads/photo_2024-05-10_08-23-23.webp" alt="" width="1154" height="320" loading="lazy" decoding="async"/>

## Criteria for choosing the best tax system: a real case

We received a request from a client who wanted to start a business but did not know which tax system suited him. He planned to provide digital marketing services and to work with bloggers and other service providers, both legal entities and individuals. He expected income of up to UAH 400,000 in the first two months and then about UAH 700,000 or more per month. Planned expenses were 80% of income, and the staff was to be up to 6 people. The client wanted to outsource accounting and reporting to an outsourcing firm.

Here are the main criteria that our experts used to give the client well-founded recommendations on the tax system for his business.

**Types of activity.** Digital marketing has no restrictions under either the simplified or the general tax system. For any other types of activity, we check whether they are on the list of activities prohibited under the simplified system.

**Main counterparties.** In this case, the simplified system at the 5% single tax rate or the general system is suitable. If most counterparties are VAT payers, it is better to register for VAT too, so as not to overpay.

**Expected turnover.** Overall, the income level in the first year of business allows the client to work under the simplified tax system. But once income exceeds 1,167 minimum wages, the business will have to switch to the general system.

**Expected expenses.** The comparison below shows which tax system is more beneficial in this case.

In our example:

<table>
<tbody>
<tr>
<td width="321">**General tax system**</td>
<td width="321">**Simplified tax system**</td>
</tr>
<tr>
<td width="321">Sales revenue excluding VAT = UAH 7,800,000</td>
</tr>
<tr>
<td width="321">Expenses = UAH 6,240,000</td>
</tr>
<tr>
<td width="321">Corporate income tax: (7,800,000 − 6,240,000) × 18% = UAH 280,800</td>
<td width="321">Single tax: 7,800,000 × 5% = UAH 390,000</td>
</tr>
<tr>
<td width="321">Under the general system, the client will have to pay UAH 280,800 of corporate income tax.</td>
<td width="321">Under the simplified system at the 5% rate, the client will have to pay UAH 390,000 of single tax.</td>
</tr>
</tbody></table>

As you can see, the tax is lower under the general tax system.

***Number of employees.** *Group III and the general system have no restrictions.

**Accounting.** In this situation, the company needs comprehensive accounting for its various work processes and regular reporting. So it is indeed better to outsource this work to professionals. This way, you can focus on growing your business and save time and money. For example, at our firm, [accounting](https://www.uhy-prostir.com/en/accounting/index.html.md) for a similar digital marketing company under the simplified tax system would cost about UAH 100,000 per year. For companies under the general system, it would cost about UAH 300,000 per year.

As you can see, there is no universal answer or single approach to choosing a tax system. A comprehensive analysis, sound arguments and recommendations from qualified professionals help you reach the best result. However, the final decision is always made by the business owner. Only the owner fully understands the business’s financial needs and strategies and has the greatest interest in maximizing profit. If you still have questions or need advice on choosing the best tax system, contact us.

Viktoriia Novodvorska [LinkedIn](https://www.linkedin.com/in/victoriia-novodvorska-06a616305)

## Related insights

- [General or Simplified Tax System for an LLC: The Case of a Digital Marketing Company](https://www.uhy-prostir.com/en/our-cases-en/choosing-a-tax-system-for-a-digital-marketing-business/index.html.md): Case study: comparing Ukraine's general tax system with the simplified system (group 3) for a digital marketing LLC, including VAT and accounting costs.
- [General or Simplified Tax System for a Law Firm: A UHY Prostir Case Study](https://www.uhy-prostir.com/en/our-cases-en/choosing-a-tax-system-for-a-law-firm-general-vs-simplified-without-vat/index.html.md): Law firm case study: comparing Ukraine's general tax system (18% profit tax) with single tax group 3 without VAT (5% + 1%) and assessing VAT.
- [FOP for IT: How to Choose KVED Codes and Pay Taxes](https://www.uhy-prostir.com/en/blog-en/it-individual-entrepreneurs-selecting-activity-codes-and-tax-compliance/index.html.md): What is specific about accounting for IT sole proprietors (FOPs) in Ukraine? IT is the most modern and the most innovative business in the country today. (2021-08-16)
- [What NGOs Should Consider When Working with Sole Proprietors (FOP) in Ukraine](https://www.uhy-prostir.com/en/blog-en/what-should-ngos-take-into-account-while-working-with-individual-entrepreneurs-flp-fop-in-ukraine/index.html.md): We continue our series on NGOs in Ukraine. This article explains what NGOs should check when they work with sole proprietors (FOP) and which risks may arise. (2023-10-02)

## Contacts

- Email: hello@uhy-prostir.com
- Address: 14 Vasylkivska St., STEND Business Center, office 315, Kyiv
- Request a proposal: https://www.uhy-prostir.com/en/contacts/#contact-form
