Setting up accounting in a company is the process of organizing and configuring an accounting system, either by building a new one or by improving the existing one, so that it meets the needs of the business and the requirements of the law. It is one of the first and most important steps in building an effective financial system for a company, and it provides order and control for years ahead.
Setting up accounting in a company requires qualified professionals. The professional UHY Prostir team can be a reliable partner in this.
What setting up accounting in a company is and who needs it
Setting up accounting is a set of actions that includes choosing accounting methods, developing the accounting policy and internal accounting rules, configuring software, creating registers and document templates, as well as training staff if needed.
Setting up accounting is essential for:
Owners and managers: to have a clear picture of cash flows, profits, expenses and the real state of the company.
Accountants: to work effectively. When the system is already set up, accounting becomes simpler and faster.
Tax authorities: to make sure that the accounts are kept properly and taxes are calculated correctly.
Investors and partners: they want to see a transparent picture before they invest money or start working with the company.
New companies: this is especially important when a business is just starting and has no established processes yet.
Setting up accounting is the basis for order and effective accounting. We agree on the rules for preparing source documents, the document flow procedure, the use of electronic digital signatures, the accounting for assets, liabilities, income, expenses and taxes, the approach to preparing reports and internal responsibilities.
Main goals of setting up accounting
Accounting in a company is, first of all, a structured set of rules that govern:
- how to record income and expenses;
- how to set the prices of goods and services;
- how to settle accounts with customers and suppliers;
- how to account for salaries, taxes and other liabilities;
- how to organize document flow and ensure compliance with the law;
- which automation system to use.
A business without a clearly built accounting system faces chaos: late reports, problems with the tax authorities, fines and no way to assess the company’s real profitability. A proper accounting system, on the other hand, provides:
Financial transparency: you always know how much you have earned and spent.
Cost control: you can optimize costs and prevent fraud.
Lower tax risks: proper accounting minimizes the tax burden and helps avoid fines.
Faster decision-making: quick access to reliable financial indicators.
Easier dealings with banks, investors and auditors: a clear financial structure increases trust in the business.
So setting up accounting is a process that defines specific rules and builds them into the system, so that the finances are well organized, easy to understand and work for the benefit of the business.
When accounting needs to be set up
A company may need to set up accounting in different situations: opening a new company, changing the tax system, reorganizing the business, scaling it up or having to meet new standards. In all these cases, setting up accounting helps put the company’s management and financial activities in order.
Main stages of setting up accounting in a company
The setup process has several important stages that make it effective and suited to the specifics of the business.
1. Analysis of the company’s current situation and needs
This stage identifies the factors that shape the accounting policy: the form of ownership, the legal form, the tax system, the types and volume of activities, the technical resources and so on. It assesses the current state of reporting, document flow and internal processes. It also reveals problem areas and sets priority tasks for further improving the accounting.
2. Developing the accounting policy
The accounting policy is the key document that sets the methods of accounting and of preparing financial statements. It defines the methods for measuring assets and liabilities, the depreciation procedure, the principles for recognizing income and expenses, materiality levels and other aspects of accounting.
3. Building the document flow system
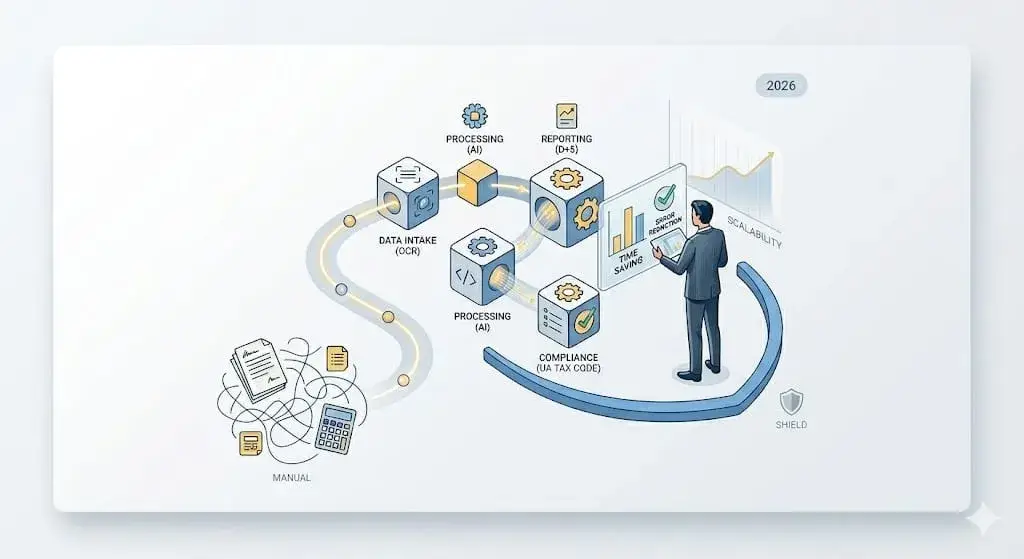
A logical structure for the flow of source documents is created, the responsible persons are appointed and processing deadlines are set. The internal control procedure and the document flow standards are also defined. Special attention is paid to electronic document flow with a qualified electronic signature (QES, an electronic signature that has the same legal force as a handwritten one). This makes work with documents more secure and convenient.
4. Implementing an accounting automation system
The final stage is configuring specialized software for automated accounting and for exchanging, storing and processing financial documents. This includes implementing modern software (ERP, CRM, accounting systems), storing documents in cloud services and integrating different systems (accounting, warehouse, sales, etc.). This creates a convenient accounting system and makes work much more efficient.
Main elements of a company’s accounting policy
As mentioned above, a company’s accounting policy is a set of accounting principles, methods and procedures. It consists of the following key parts.
Accounting for income and expenses
It is based on clearly defined rules and approaches to recognizing income and expenses that reflect the specifics of the company’s activities. This not only makes cash flows transparent, but also creates a reliable basis for analysis and management decisions.
Accounting for assets and liabilities
This covers keeping records of fixed assets, inventories and liabilities and choosing suitable methods for depreciating fixed assets, writing off inventories and revaluing assets. Together, they ensure accurate data for cost optimization, planning and control.
Tax accounting
Tax accounting includes defining the approaches to calculating taxes and to accounting for VAT, corporate income tax and the single tax (under Ukraine’s simplified tax system, if applicable). It also covers dealing with the regulatory authorities. A properly set up tax policy helps avoid violations and fines.
Benefits of an accounting policy for a company
Keep in mind the main purpose of an accounting policy. It unifies and standardizes, within the company, the processes that are important for its activities but are open to different interpretations or not regulated at the state level at all. An accounting policy not only makes the accounting department’s work easier, but also brings a number of benefits to the whole company:
For management: a clear understanding of the financial position and easier planning and decision-making thanks to structured reporting. An accounting policy provides the reliable financial, operational and time-related data needed to measure key performance indicators (KPIs), for example, expenses, profit or inventory turnover. It also provides the data to track progress toward objectives and key results (OKRs) related to income and process optimization.
For employees: simpler work with documents and less routine thanks to unified and automated processes.
For owners: a lower risk of fines thanks to compliance with the law and greater transparency of transactions.
For partners and customers: fast processing of deals and documents, which increases trust and competitiveness.
So a well-designed accounting policy not only reduces chaos in accounting processes, but also strengthens the company’s ability to work with goals and indicators.
Benefits of working with a professional firm to set up accounting
Experience and expertise
UHY Prostir has more than 18 years of experience in implementing accounting systems and setting up accounting for different types of business, from small companies to large corporations in trade, manufacturing, IT and logistics.
Knowledge of the law
Our team constantly follows changes in the law and assists clients in avoiding violations and fines. For each client, we develop an accounting policy that follows only up-to-date standards, legal requirements and the specifics of the client’s business.
A tailored approach
We offer tailored solutions for each client. For example, for IT companies, we take into account the specifics of development costs, and for manufacturers, inventory management. A flexible approach makes accounting effective and suited to your needs.
How to order accounting services
Setting up accounting, which covers document flow and the accounting policy, is the first step toward transparent and effective work for a company. At UHY Prostir, we make it part of our full accounting service, so you get not just a setup but full ongoing assistance. We will take care of your accounting so that you can focus on growing your business. To get started, follow a few simple steps:
- Submit a request on our website.
- Initial consultation: a personal manager identifies your business needs.
- Pricing: we analyze the scope of work and provide a cost estimate.
- Signing the agreement: we agree on the terms of cooperation.
- We start work on your project and keep your accounts.
The procedure is simple and clear, and our team will assist you at every stage.